If you have been looking into air conditioning, you may have seen “0% VAT” mentioned. It is real, but it comes with conditions, and plenty of what gets repeated online is a bit loose. Here is a plain-English summary of what HMRC’s own guidance says, what it means for a typical home, and how to find out whether your installation qualifies.
Where the 0% VAT rule comes from
The rule sits in HMRC’s VAT Notice 708/6: Energy-saving materials and heating equipment. It is worth reading the notice itself if you like detail. The key points are below.
- A zero rate of VAT applies to the installation of certain energy-saving materials from 1 May 2023 to 31 March 2027.
- From 1 April 2027, the notice says these installations will go back to the reduced rate of 5%, not the standard 20%.
- Air source heat pumps are on the list of qualifying energy-saving materials, along with ground source and water source heat pumps.
- Only air source heat pumps that are permanently fixed qualify. Portable or moveable units do not.
- The relief applies to installations in residential accommodation (and certain charitable buildings). Hotels and similar establishments are standard-rated.
- If materials are supplied without being installed, the supply is standard-rated. Buying a unit online and fitting it yourself does not qualify.
So does air conditioning count?
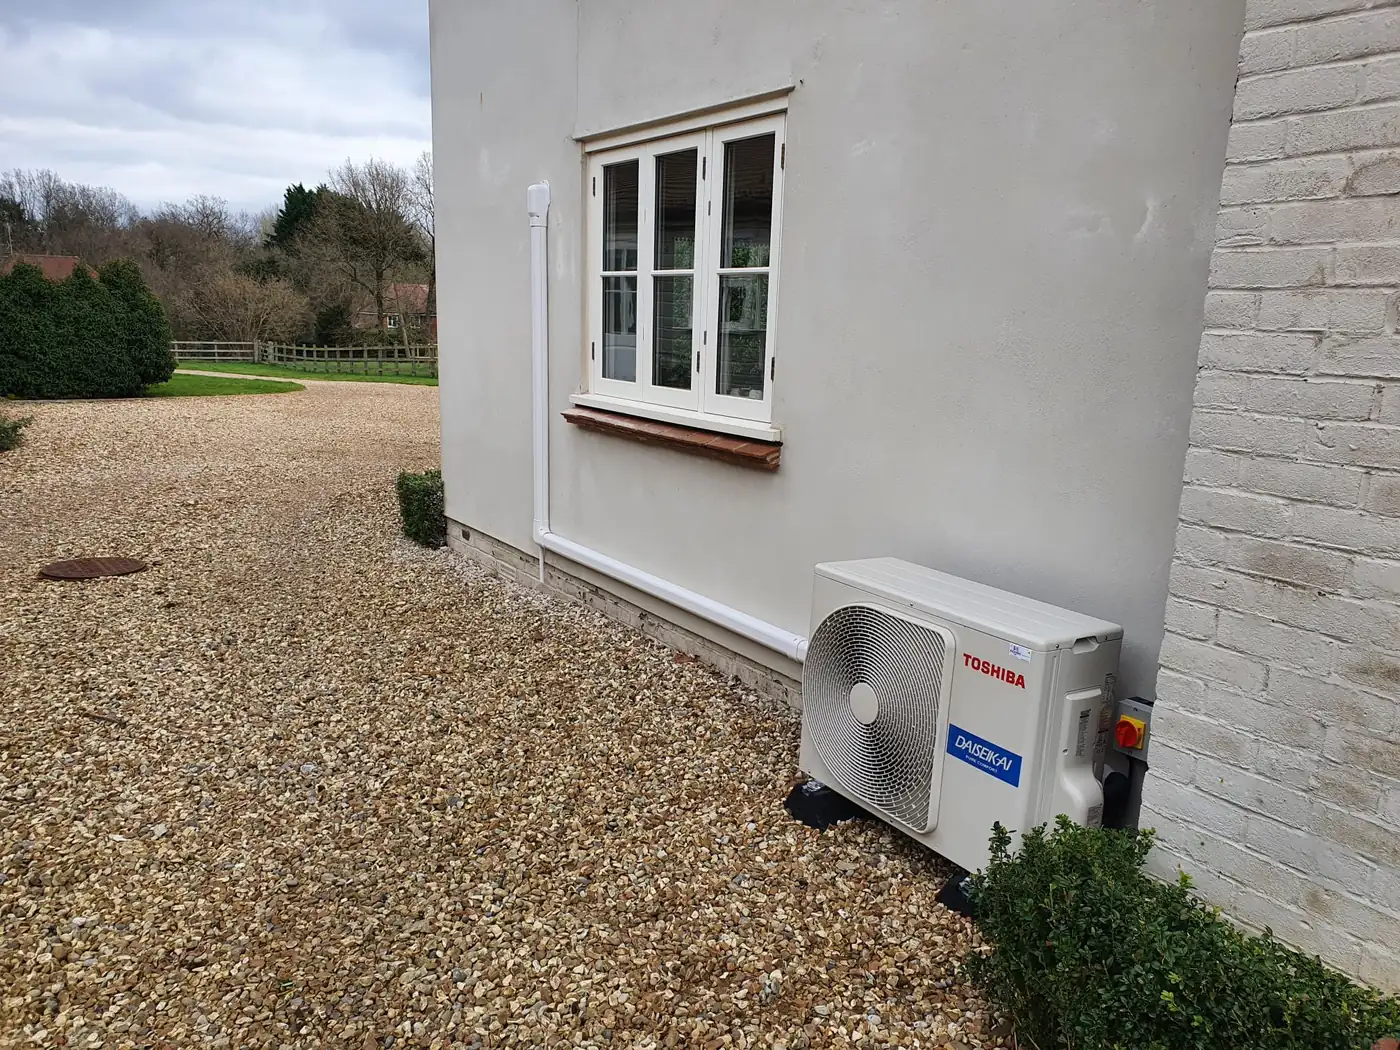
This is the part that matters most, so here is exactly what the notice says. HMRC describes fixed air source heat pumps that can be reversed to provide cooling in summer as well as heating in colder months. It then says that HMRC’s understanding is that most air conditioning units are air source heat pumps, and that borderline cases depend on the facts of each case.
In practice, that means a modern, fixed, reverse-cycle system installed in your home may well qualify. It does not mean every product sold as “air conditioning” automatically does, and the notice does not name air-to-air systems specifically. So our honest answer is: ask us whether your installation qualifies. We will look at the system we are proposing and the property, and tell you clearly how VAT is being treated on your quote.
What the saving looks like in numbers
We are not going to quote you a made-up price, because every home is different. But the arithmetic is simple and worth knowing:
- At the standard 20% rate, every £1,000 of work before VAT would cost £1,200.
- At the reduced 5% rate (which the notice says applies from 1 April 2027), the same £1,000 would cost £1,050.
- At 0%, where the installation qualifies, it costs £1,000.
If your installation qualifies, the zero rate is simply applied on the invoice. There is nothing for you to claim back afterwards.
Which homes and jobs are covered?
Homes, not businesses
The notice talks about residential accommodation: houses, flats and other dwellings, plus some care homes, student and holiday accommodation. Offices, shops and hotels are not covered. If you run a business from home, or the property is mixed use, talk to us early so the quote is set up correctly. HMRC’s notice does not give much detail on mixed-use buildings, so that is one to check rather than assume.
Installed, not just supplied
The relief is on the supply and installation together. That is one more reason to use a properly qualified installer: an air conditioning system has to be connected, pressure tested, evacuated and commissioned by someone who is F-Gas certified. We are F-Gas certified and REFCOM registered (REF1024334).
Heat pumps for heating and hot water
The same notice covers air source heat pumps that heat your home and hot water, which is often a cleaner fit with the rules. If you are weighing up a heat pump for central heating rather than air conditioning, see our heat pumps page.
What about boilers?
Gas and oil boilers are a different story. Under the notice, they only get a reduced rate in specific grant-funded situations. Most boiler replacements are standard-rated. Our boiler installation prices are always shown with VAT included, so there are no surprises.
Is it worth acting before 31 March 2027?
If you were already planning air conditioning or a heat pump, the deadline is worth keeping in mind. On the notice as it stands, a qualifying installation completed after 31 March 2027 would carry 5% VAT rather than 0%. That is a real but modest difference, so it should not be the only reason to buy.
The bigger question is whether the system is right for your home. A good survey, sensible sizing and a neat installation matter far more over ten or fifteen years than the VAT line on the invoice. If it would help, our guide Do I actually need air conditioning in the UK? is a straight look at when it makes sense.
Tax rules change. We have summarised HMRC’s guidance as published, but always check the current notice on GOV.UK and ask us to confirm how VAT applies to your own quote.
How we handle VAT on your quote
- We look at the system and the property, and tell you how VAT is being applied before you commit.
- Our Fixed-Price Guarantee means the price we quote is the price you pay.
- Quotes usually arrive within 24 to 48 hours of your survey.
- We are a VAT-registered company (VAT 518 2435 96), so everything is properly invoiced.
You can see typical prices on our prices page, read about our air conditioning installation service, look at air conditioning case studies, or get your free quote.
Questions we get asked
Is all air conditioning zero-rated for VAT?
No. HMRC’s understanding is that most air conditioning units are air source heat pumps, but each case depends on the facts. The system must be permanently fixed, installed by the supplier, and in residential accommodation. Ask us and we will confirm for your installation.
When does the 0% rate end?
The notice says the zero rate applies from 1 May 2023 to 31 March 2027. From 1 April 2027 it says the reduced rate of 5% applies.
Can I get 0% VAT on a portable air conditioner?
No. The notice says only air source heat pumps that are permanently fixed, and not portable or moveable, qualify.
Does it apply to my business premises?
Generally not. The relief covers residential accommodation and certain charitable buildings. Hotels and similar establishments are standard-rated.
Do I have to claim the VAT back?
No. If the installation qualifies, the correct rate is applied on the invoice.
Ready when you are
Tell us what you need and we will come back to you with a clear, fixed price. No pressure, no hard sell.
Ready when you are
Tell us what you need and we will come back to you with a clear, fixed price. No pressure, no hard sell.